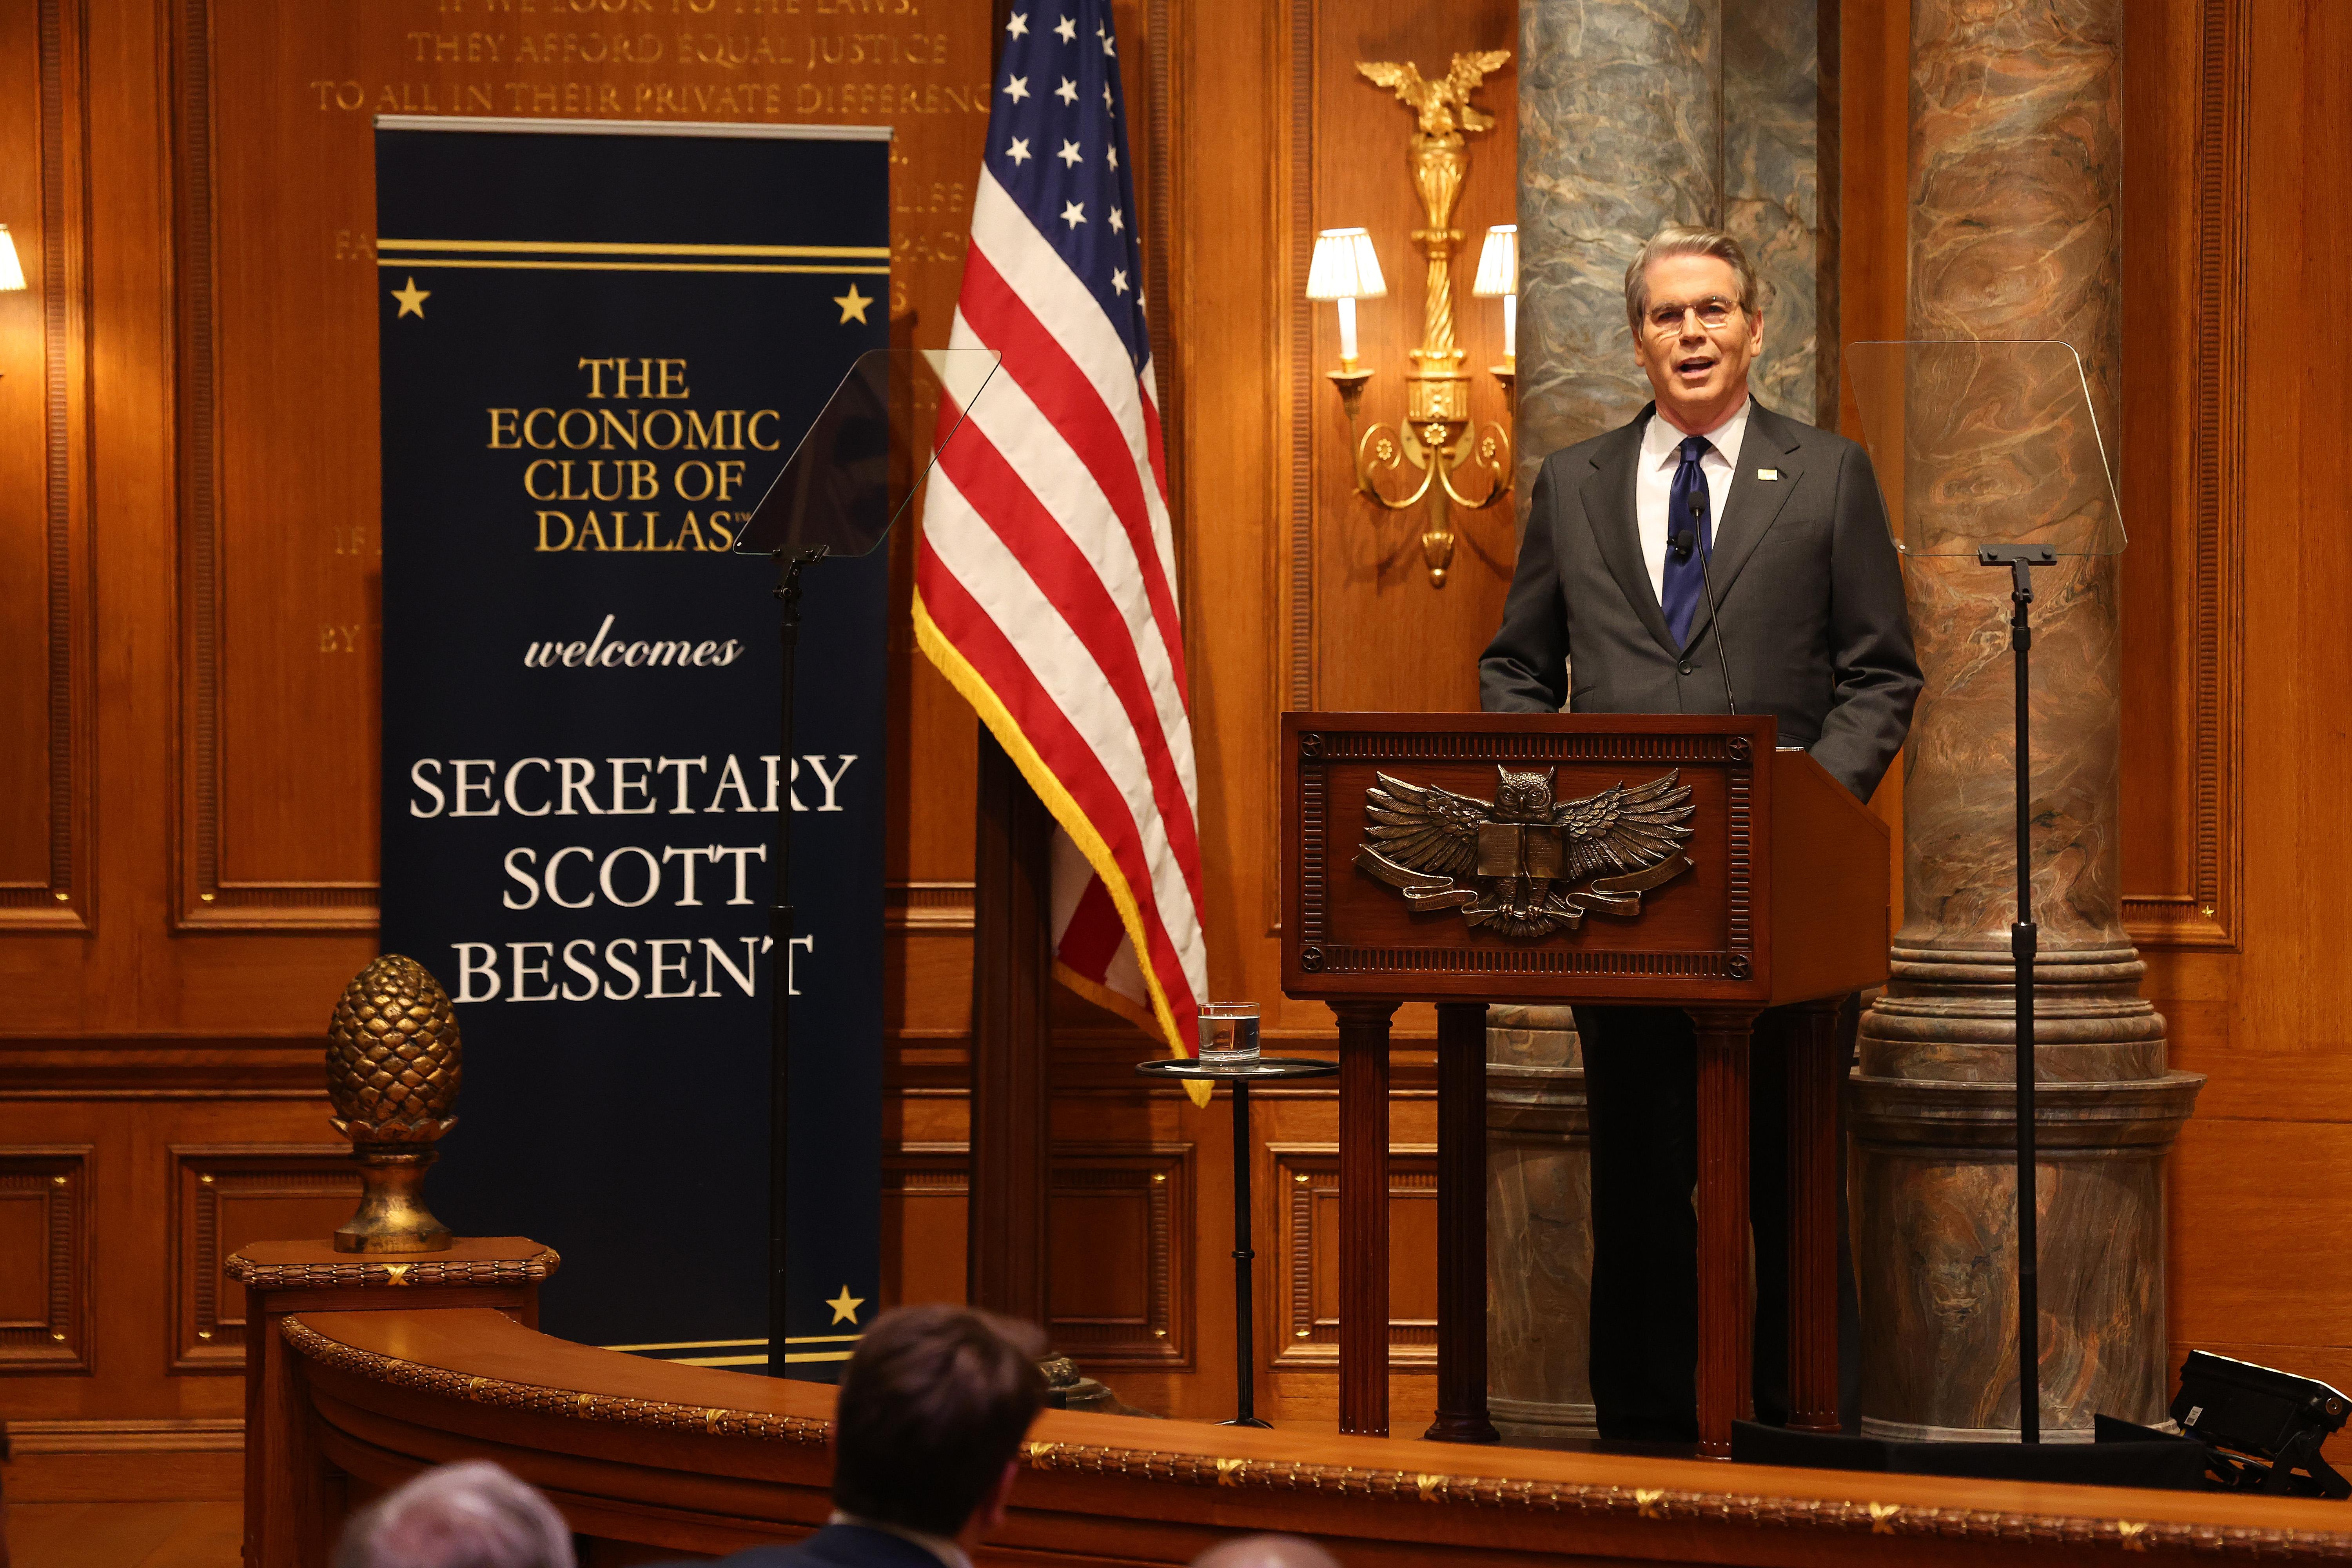
Treasury Secretary Scott Bessent Signals Flexibility in Debt Management Amidst Yield Volatility
What's Happening?
Treasury Secretary Scott Bessent's department has announced that the sizes of note and bond sales will remain unchanged for the next several quarters, a move that keeps options open for future adjustments.
This decision follows a period where 30-year Treasury rates reached their highest levels since 2002, despite earlier attempts by the Treasury to cool rising yields through an unanticipated enlargement of buybacks. The August debt management plan had already shifted language from 'increases' to 'changes' regarding future coupon and floating rate note sales, a phrasing that has been maintained. The Treasury also indicated it would engage with market participants to better understand evolving supply and demand dynamics. This approach has led dealers to re-evaluate their outlooks for upcoming auctions, as some had anticipated a stronger signal for adjustments within the next six months. The announcement proved tamer than some bolder scenarios, initially causing the curve to steepen before a decline in oil prices pulled yields lower across the curve.
Why It's Important?
This measured approach by the Treasury is significant because it reflects a cautious stance in managing the national debt amidst volatile market conditions. By keeping auction sizes unchanged for now, the Treasury avoids immediate drastic shifts that could further destabilize yields, while also signaling flexibility for future adjustments. This impacts U.S. financial markets by influencing investor expectations for Treasury supply and demand, which in turn affects borrowing costs for the government and interest rates across the economy. The emphasis on understanding market dynamics suggests a data-driven approach to debt management, aiming to finance the government at the lowest cost over time. The market's reaction, including the initial steepening of the curve and subsequent yield declines, highlights the sensitivity of financial markets to Treasury communications and the broader economic environment, such as oil prices. This strategy aims to balance the need for stable financing with responsiveness to market signals, affecting bond investors, financial institutions, and ultimately, the cost of capital for businesses and consumers.
What's Next?
Market participants will closely monitor future Treasury communications for any hints of strategic shifts, particularly regarding the mix of debt maturities. While current auction sizes are stable, the Treasury Borrowing Advisory Committee (TBAC) has suggested that if more supply is needed, the focus should be on the 2 to 10-year sector rather than longer maturities. This indicates a potential shift in duration risk away from 20- and 30-year bonds. Investors will be watching for whether coupon rates pick up as late 2027 approaches and if the May refunding announcement signals any trims to the long end of the yield curve. The evolution of the $6 billion buyback cap will also be a key indicator. These decisions will shape the yield curve and how new Treasury supply meets demand across different maturities, influencing investment strategies and the broader financial landscape. The Treasury's ongoing engagement with market participants will be crucial in guiding these future adjustments.
Beyond the Headlines
The Treasury's nuanced communication reflects a delicate balancing act between maintaining market predictability and adapting to evolving economic realities. The subtle shift in language from 'increases' to 'changes' and the commitment to engage with market participants underscore a move towards more adaptive debt management. This approach could signify a long-term shift in how the U.S. Treasury manages its debt, moving away from rigid, pre-announced schedules towards a more dynamic, responsive framework. The increased reliance on shorter-term bills to finance deficits, which makes debt service costs more sensitive to interest rate shocks, highlights a structural vulnerability. This sensitivity could influence future Federal Reserve policy decisions, as higher short-term rates would directly impact the government's borrowing costs. The ongoing evaluation of buyback enhancements also suggests a proactive stance in managing market liquidity and volatility, potentially setting a precedent for how central banks and treasuries interact with bond markets in times of economic uncertainty.